WinCrown · Welcome bonus200 free spins on selected slots
Reviews (9,827)
4.9Rating
Verified guide
An online casino PayID withdrawal is a bank transfer the operator’s payment processor sends to the phone number or email you have registered as a PayID with your own Australian bank. You can deposit by PayID at many offshore casinos that take Australian players, but paying in that way does not guarantee you can be paid out the same way: each site lists its payout methods separately, and some offer PayID for deposits only. The transfer itself is quick once it is sent. Nearly all of the waiting happens earlier, inside the casino, while the request is reviewed and approved.
For a deposit you need an account with an Australian bank that supports PayID, a casino balance held in AUD, and the payee details shown in the cashier at that moment, since they can change between visits. Minimum amounts are set by each operator and differ between paying in and cashing out. For a withdrawal, the PayID has to be registered in your own name, matching the name on the casino account, and your identity will normally be checked before the first payout. Some banks hold or decline payments linked to gambling, and that is the bank’s decision, not the casino’s.
 Best casinos available in AustraliaUpdated 7 November 2026
WinCrown · Welcome bonus200 free spins on selected slots
Reviews (9,827)
4.9Rating
PayID is not a wallet and it does not hold money. It is an address: a mobile number, an email or an ABN that your bank links to one of your accounts, so that someone can pay you without knowing your BSB and account number. The payment travels over Australia’s New Payments Platform, usually as an Osko transfer, and reaches the linked account in close to real time, on weekends and public holidays as well as business days.
So when a cashier offers a PayID withdrawal, it is offering a domestic bank transfer addressed to your PayID. The casino does not send it directly. Offshore operators route Australian payouts through third-party payment processors with access to local banking, and it is the processor’s account that appears as the sender on your statement. The name may be a company you have never heard of. That is normal, though it is also why you should match the amount and time against your withdrawal request.
Two consequences follow. The speed of the rail tells you little about the speed of the payout, because the transfer is the final step of several. And there is no PayID company to complain to if something goes wrong. Your relationship is with the casino on one side and your own bank on the other.
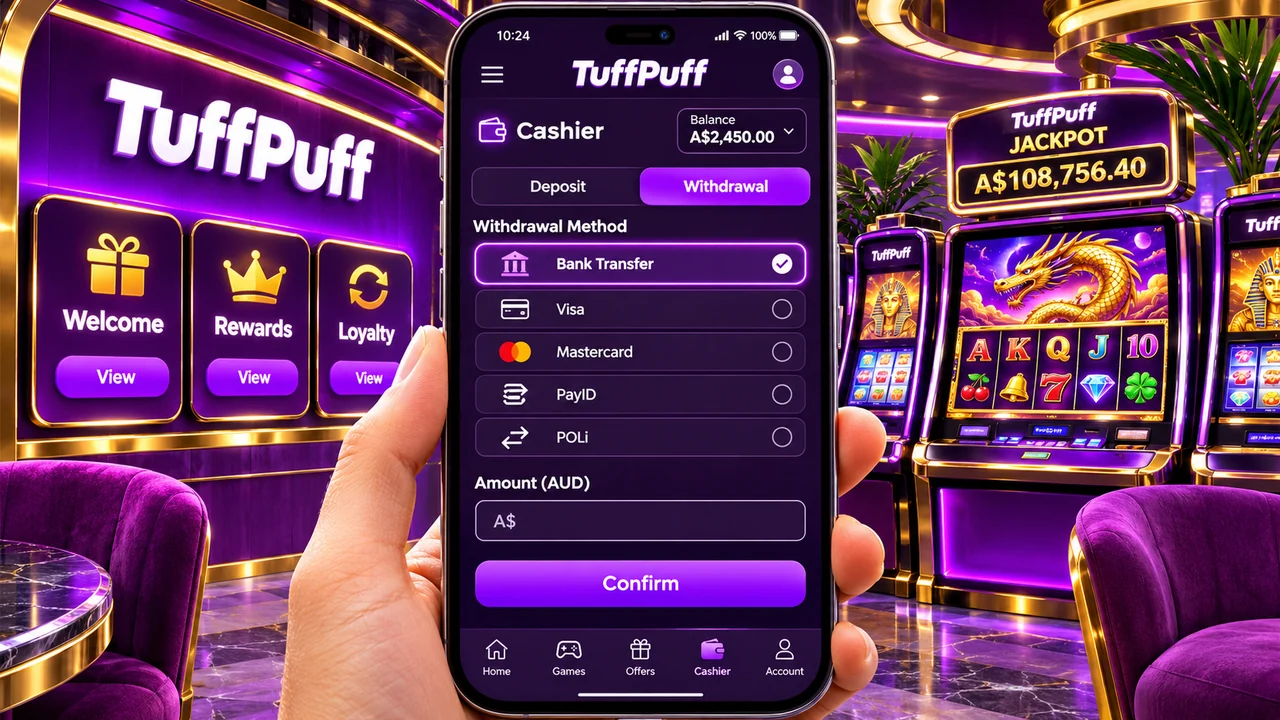
The most common misunderstanding is assuming a method in the deposit menu will be waiting in the withdrawal menu. They are separate lists. A site can accept PayID deposits through one processor and have no arrangement for sending money back along the same rail. In that case the payout tab shows ordinary bank transfer, crypto or an e-wallet, and PayID is simply absent.
Check before you deposit, not after you win. Log in, open the cashier and click through to the withdrawal side. Most sites show the available methods even with an empty balance. If the list is hidden until you have funds, ask live chat a direct question: can I withdraw to a PayID, what is the minimum, and how long does approval take? Save the reply.
A related rule catches people too. Many operators pay out to the method used for the deposit wherever possible, as an anti-money-laundering measure. If you deposited by voucher or card and then ask for a PayID payout, the site may send part of the money back to the original method first, or ask for extra proof that the bank account is yours. It is slower, not sinister, and it is avoidable if you plan the route in advance.
Advertised payout speeds usually describe the last stage only. A fairer picture breaks the journey into the stages below. No operator’s actual times are quoted here, because they vary by site, by day and by the state of your account.
| Stage | Who controls it | What slows it down |
|---|---|---|
| Request lodged | You | Unfinished wagering, a balance under the minimum, an active bonus |
| Pending period | Casino | A fixed window in which the request can still be reversed |
| Review and approval | Casino payments team | Unverified identity, weekend staffing, a large or unusual win |
| Sent to processor | Payment processor | Batch runs, the processor’s own limits and checks |
| Bank transfer | The two banks | A security hold on a first payment from a new sender |
Read the table from the bottom up and the picture is clear. The banking leg is usually seconds or minutes. A first payment from an unfamiliar sender can occasionally be held for a security check, but that is the exception. The stages in the middle are where a payout sits for hours or days, and they are entirely in the operator’s hands.
The pending period deserves a warning. While a request is pending, many sites let you cancel it and return the money to your balance. It is presented as a convenience. In practice it is the point at which a good share of withdrawals are played back. If the site offers a way to lock a request, use it, and if not, stay out of the lobby until the money has landed.
Most failed PayID payouts come down to a detail on the receiving end. Create the PayID in your banking app before you need it, and note three things: the identifier you chose, the account it is linked to, and the name the bank displays to people who pay you. That display name is what the processor sees when it looks your PayID up, and it is the first thing checked against your casino profile.
One more practical point. Payee details shown for deposits can change from one visit to the next, because processors rotate their receiving accounts. Never reuse an old PayID from a previous deposit, and never pay one sent to you by email or chat outside the logged-in cashier.
Expect to prove who you are before any money leaves, whatever the amount. Operators ask for photo identification, a recent proof of address, and often proof that the receiving bank account is yours. For PayID, that last item is usually a bank statement or a screenshot from your banking app showing your name, BSB and account number, with balances and unrelated transactions covered if the site’s instructions allow it.
The timing is the frustrating part. Many players are asked for documents only when they request a first withdrawal, which adds the review time to the payout time. You can take that delay out yourself. Upload the documents straight after registering and ask support to confirm the account is verified before you play. A site that will not verify you until you have won is telling you where its priorities lie.
Rejected documents are nearly always a quality problem: a cropped corner, glare across the photo, an address document older than the site accepts, or a name that differs between the ID and the bank proof. Send the whole document, flat, in good light, in the file format requested. If something is rejected, ask which specific element failed instead of resubmitting the same file.
Every payout method has a floor and a ceiling, and both are set by the operator. The floor matters to small players: if the minimum PayID withdrawal is above your balance, the money cannot leave by that route. The ceiling matters after a big win. Sites commonly cap how much can be withdrawn per transaction, per day, per week or per month, and a large balance is then paid in instalments.
Your own bank adds another layer. Banks set daily limits on fast payments, mainly on the sending side, and may review an unusually large incoming transfer. Neither the casino nor the processor can change that. If you expect a sizeable payout, a call to your bank beforehand costs nothing.
On fees, look in two places. The casino’s payments terms state whether a charge applies to bank withdrawals and whether a number of free payouts is allowed per period. Your bank does not normally charge to receive an Osko payment. Currency is the hidden cost: if your casino balance is not in Australian dollars, the conversion happens at the operator’s or processor’s rate before the transfer is made. An AUD account avoids that entirely, and the currency is normally fixed at sign-up.
The sequence below is an illustration with invented figures and times. It shows how the pieces fit, not what any particular operator does.
The bank transfer took minutes. The payout took most of three days. Had her account been unverified, the document review would have been added on top. Had she asked on a Tuesday morning, the same request might have been finished by the afternoon. When you compare sites, the questions that matter are how long the pending period lasts and whether approvals are done on weekends.
If the cashier does not offer PayID for withdrawals, you still have options, each with its own trade-off.
| Method | How it compares | The catch |
|---|---|---|
| Standard bank transfer | Same destination, slower route | May take business days and can involve an intermediary bank |
| Crypto | Fast once approved | Price moves, network fees, and you need a wallet you control |
| E-wallet | Usually quick | A further step and possible fees to move funds to your bank |
| Card refund | Limited to amounts deposited by card | Not available at every site or for every card |
A standard bank transfer to your BSB and account number is the closest substitute. The money ends up in the same place. An international wire is different: it can pass through intermediary banks, arrive short by their charges, and take several business days. Ask which kind the site sends before you agree to it.
Crypto payouts suit people who already hold a wallet and understand the exchange step back to dollars. They are a poor first experiment with a large win at stake. Whatever the route, the verification, limits and pending period described above still apply, because they belong to the casino and not to the payment method.
Be realistic about the last step. An offshore licensing body is not an Australian regulator and has no power here. Its willingness to act varies a great deal. That is the practical reason to test a site with a small withdrawal early, before a larger balance depends on its goodwill.
PayID’s popularity has made it a favourite prop for fraud, and a few patterns target casino players directly. The first is the fake fee: a message claiming your withdrawal is ready but your PayID needs an upgrade, a business account or a release payment before the money can be sent. PayID is a free service provided through your bank. It does not email or text customers, it has no account tiers, and nobody needs to be paid to receive a payment.
The second is the cloned cashier. A lookalike site, often reached through a link in a message or a social media advert, shows a PayID that belongs to the scammer. Money sent to it is gone, and a fast payment generally cannot be recalled once it has been accepted. Type the casino address yourself, pay only from inside your logged-in account, and read the payee name your bank displays before you approve.
The third is the helpful stranger offering to cash out for you through their own account for a cut. That hands your money to someone with no obligation to return it and breaches the operator’s terms as well. If you think you have paid a scammer, call your bank straight away and report it to Scamwatch.
Online casino games cannot lawfully be offered to people in Australia. The Interactive Gambling Act 2001 puts the offence on the operator, and ACMA has sites blocked on that basis. Playing is not an offence for the individual, but it does mean every casino that pays out by PayID to an Australian account is an offshore business outside the reach of South Australian consumer and gambling regulation. The venue rules we cover in our South Australian pokies law guide do not extend to it.
That is why this page concentrates on what you can verify yourself. The operators shown at the top are this guide’s commercial partners, the placement is sponsored, and our review process explains what we look at before one appears. If you arrived here with a free offer in mind, the payout questions for that case are covered in our walk-through of no deposit codes. Gambling is for adults aged 18 and over; set a limit before you deposit and stick to it.
There is no single answer, because the wait depends on the site’s approval process far more than on the banking system. A verified player asking on a weekday will generally be paid sooner than a new player asking on a Saturday night.
Sometimes. Many sites prefer to return funds along the original deposit route first, and may want proof that the bank account behind the PayID is yours before sending winnings there.
Offshore casinos use local payment processors, and it is the processor’s trading name that shows on your statement. Confirm the amount and timing against your request, and ask support for the reference if you are unsure.
For most people in Australia, gambling winnings from recreational play are not treated as taxable income. Anyone whose circumstances are unusual should get advice from a registered tax agent.
Banks can hold or query transfers they consider unusual, and some take a firm line on gambling-related transactions. If a payment is held, your bank will usually release it after speaking to you, so answer their call or message promptly.
No. An existing PayID in your own name works, provided the linked account can receive fast payments. Some players prefer to register their email as a separate identifier for a dedicated account, which keeps gambling transactions apart from everyday banking.
Advertisement · 18+
A venue has opening hours and a dress code. Online the pokies, the live roulette and the sport are open at any hour, with a demo mode before you stake anything.
See the current offer